Singapore Holding Company Structure for Global Groups
As businesses expand across international markets, managing multiple subsidiaries, investments and cross-border transactions becomes increasingly complex. A company operating in several countries may face different tax systems, regulatory requirements, ownership arrangements and financial reporting obligations.
For multinational groups, choosing an appropriate holding company jurisdiction can play an important role in simplifying ownership, improving corporate governance and supporting future expansion.
Singapore has emerged as an attractive location for international holding structures because of its established legal framework, developed financial ecosystem, international connectivity and extensive network of tax treaties.
A singapore holding company can provide a central ownership structure for subsidiaries and investments across multiple jurisdictions. However, its effectiveness depends on how the group is organised, where management decisions are made and whether the structure satisfies applicable regulatory and tax requirements.
This guide explains how Singapore holding companies work, the structures available to global groups, potential tax considerations, incorporation requirements and important compliance obligations.
What Is a Singapore Holding Company?
A holding company is an entity established primarily to own shares or other investments in subsidiary companies.
Unlike an operating company, which directly sells products or provides services, a holding company may focus on ownership, investment management, corporate governance and strategic oversight.
A holding company in singapore can own shares in businesses incorporated in Singapore or other countries.
For example, an international business group may establish a Singapore parent company that holds equity interests in subsidiaries operating in India, Indonesia, Australia and other markets.
Each subsidiary can continue conducting its local commercial activities while the Singapore entity serves as the central ownership company.
Depending on the group's requirements, the holding company may also undertake treasury, management or other functions. These activities must be properly documented and supported by actual commercial operations.
How Does a Singapore Holding Company Structure Work?
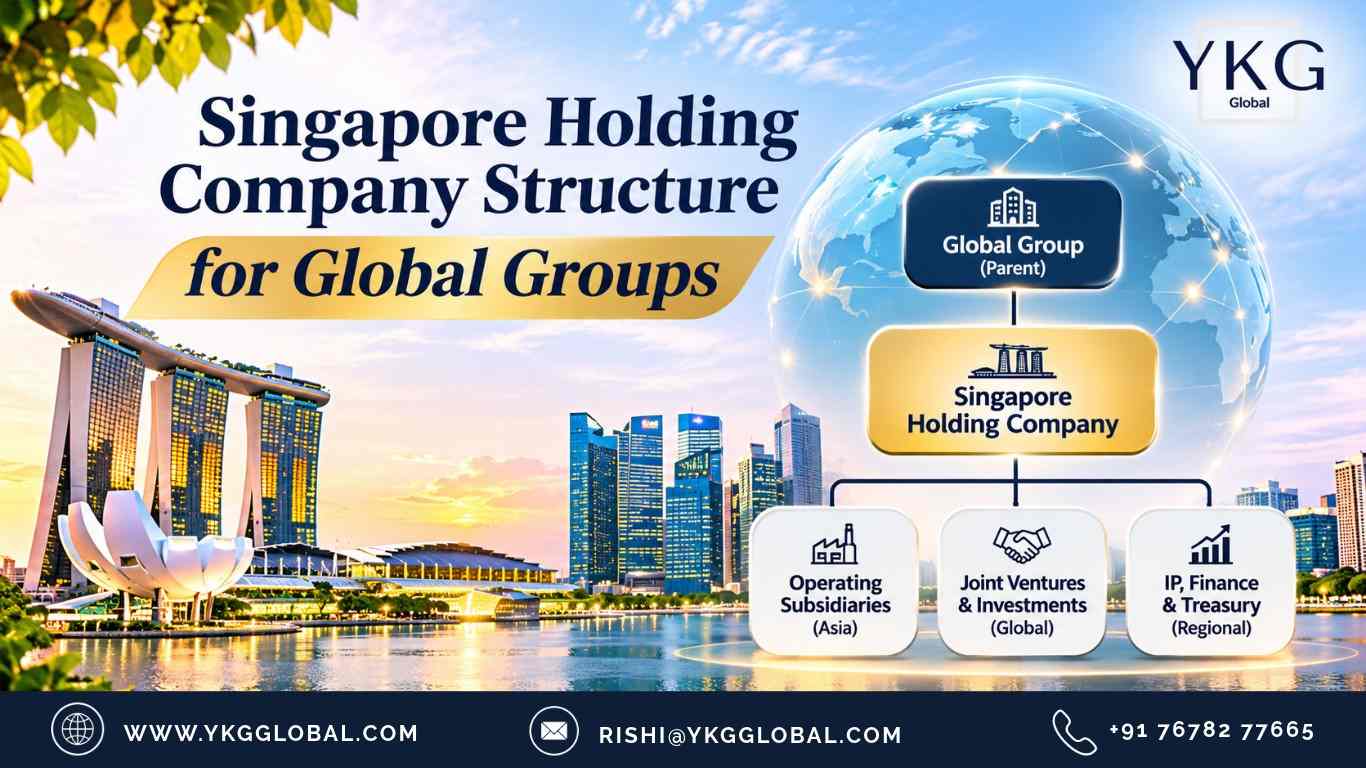
A typical singapore holding company structure involves a parent entity incorporated in Singapore and one or more subsidiary companies operating in different jurisdictions.
Consider an international technology group planning to expand across Asia.
Its ownership arrangement might be:
Singapore Holding Company (Parent Entity)
1. Indian subsidiary – Software development and technical support.
2. Indonesian subsidiary – Regional sales and distribution.
3. Australian subsidiary – Customer acquisition and consulting.
4. Singapore subsidiary – Regional management and commercial operations.
Under this arrangement, the Singapore holding company owns shares in the operating subsidiaries.
The subsidiaries conduct their respective business activities, generate revenue and meet local regulatory obligations.
Subject to applicable laws and corporate approvals, the subsidiaries may distribute profits to their shareholder through dividends.
The holding company may then retain funds for investment, distribute dividends to its own shareholders or finance further expansion.
However, dividend payments and intercompany financing arrangements may trigger withholding taxes, reporting requirements and other obligations in the relevant countries.
The structure must therefore be evaluated at both the Singapore level and the subsidiary jurisdiction level.
Why Do Global Groups Choose Singapore for Holding Companies?
Singapore offers several characteristics that make it relevant for international corporate structuring.
1. Established Legal and Regulatory Framework
Singapore has a well-developed corporate legal system and clearly defined requirements for company incorporation, ownership and governance.
The Accounting and Corporate Regulatory Authority (ACRA) administers company registration and statutory corporate filings.
For international investors, a structured regulatory environment can provide greater clarity when establishing and maintaining a parent company.
2. Access to International Markets
Singapore's location and commercial relationships make it an attractive base for groups operating across Southeast Asia and other regions.
A holding company can provide centralised ownership while operating subsidiaries maintain their local market presence.
3. Developed Financial Ecosystem
Singapore has an established banking, investment and professional services sector.
This can support corporate groups requiring international banking, treasury management, financing and transaction advisory services.
Access to specific banking products remains subject to the financial institution's independent approval.
4. International Tax Treaty Network
Singapore has an extensive network of agreements for the avoidance of double taxation.
These treaties may help address cross-border taxation of dividends, interest, royalties and other income, subject to the relevant provisions.
Treaty benefits are not automatic. The company must satisfy applicable tax residency, beneficial ownership, anti-abuse and other eligibility requirements.
5. Corporate Governance and Investment Management
A Singapore parent company can provide a central ownership and governance structure for international subsidiaries.
This may simplify shareholder arrangements, investment decisions and group-level reporting.
However, effective governance requires more than appointing directors. Decision-making processes and management responsibilities must reflect the company's actual activities.
Different Types of Singapore Holding Company Structures
Not every multinational group requires the same holding arrangement.
The most appropriate structure depends on the group's ownership, investment strategy, business activities and future plans.
1. Pure Investment Holding Company
A pure investment holding company primarily owns equity interests and receives income such as dividends or gains from investments.
It generally does not undertake substantial operating activities.
This structure may be considered by groups seeking centralised ownership of subsidiaries or long-term investments.
However, pure investment holding companies may face particular tax residency and economic substance considerations.
2. Regional Holding Company
A regional holding company owns subsidiaries operating within a particular geographical region.
For example, a European group expanding into Southeast Asia may establish a Singapore holding company to own its regional operating subsidiaries.
The arrangement can help organise investments and regional corporate governance.
3. Intermediate Holding Company
An intermediate holding company sits between the ultimate parent company and operating subsidiaries.
For example, a parent company based in another jurisdiction may own a Singapore entity, which in turn holds shares in Asian subsidiaries.
Such structures require careful assessment of commercial purpose, tax treaty eligibility and anti-avoidance rules.
4. Holding and Management Company
Some groups establish a Singapore company that combines equity ownership with genuine regional management functions.
These functions may include strategic planning, procurement coordination, treasury management or other services.
Where the company charges subsidiaries for services, related-party pricing and documentation requirements must be considered.
Singapore Holding Company Tax Benefits: What Businesses Should Know
Taxation is an important consideration when evaluating a holding structure.
However, singapore holding company tax benefits depend on the company's circumstances, income sources, tax residency and applicable legislation.
1. Corporate Income Tax
Singapore's headline corporate income tax rate is 17% of chargeable income.
Eligible companies may benefit from applicable tax exemptions or reliefs.
However, companies whose principal activity is investment holding are generally excluded from the tax exemption scheme for new start-up companies.
Other tax reliefs may be available where the relevant conditions are satisfied.
2. Foreign-Sourced Dividend Income
Singapore tax-resident companies may qualify for an exemption on certain foreign-sourced dividends received in Singapore.
The exemption generally requires satisfaction of prescribed conditions, including the foreign tax and headline tax rate tests, as well as the requirement that the exemption be beneficial to the company.
The applicable rules must be assessed based on the income and jurisdiction concerned.
A dividend received from an overseas subsidiary is therefore not automatically exempt from Singapore tax.
3. Capital Gains and Disposal of Investments
Singapore generally does not impose tax on genuine capital gains.
However, gains from the disposal of investments may be taxable where they are revenue in nature or fall within specific statutory provisions.
Importantly, Singapore's foreign-sourced disposal gains regime, effective from 1 January 2024, can apply to certain gains from foreign assets received in Singapore by entities within relevant multinational groups.
Economic substance requirements and other statutory exceptions may influence the tax treatment.
Groups planning acquisitions, restructuring or exits should assess these rules before disposing of overseas investments.
4. Dividend Distributions
Under Singapore's one-tier corporate tax system, dividends paid by Singapore-resident companies are generally not subject to further Singapore income tax in shareholders' hands.
Singapore also generally does not impose withholding tax on dividend distributions.
However, overseas shareholders may have tax obligations in their countries of residence.
The overall tax outcome must therefore be assessed across the entire ownership chain.
Tax Residency and Economic Substance Requirements
One of the most important issues for foreign-owned holding companies is determining whether the entity qualifies as a Singapore tax resident.
A company's tax residency generally depends on where its control and management are exercised.
Incorporation in Singapore alone does not automatically establish Singapore tax residency.
For foreign-owned investment holding companies earning passive or foreign-sourced income, the Inland Revenue Authority of Singapore may require particular scrutiny of the company's management arrangements.
Relevant considerations may include:
1. Where strategic decisions are made.
2. The role and responsibilities of directors.
3. Where board meetings are conducted.
4. Whether directors exercise genuine decision-making authority.
5. The nature of the company's business activities.
6. The commercial reasons for establishing the Singapore entity.
Economic substance is also relevant under certain tax provisions, including the foreign-sourced disposal gains regime.
A pure equity-holding entity may be subject to different substance criteria from an entity undertaking broader business activities.
The specific requirements must be assessed under the relevant legislation.
Appointing a local director or maintaining a registered office does not, by itself, guarantee tax residency or economic substance.
How to Set Up a Singapore Holding Company
The process of singapore holding company setup begins with defining the intended ownership and investment structure.
Step 1: Evaluate the Group Structure
Identify the ultimate shareholders, existing subsidiaries and proposed investment arrangements.
Consider whether the Singapore entity will serve as an ultimate parent, regional parent or intermediate holding company.
Step 2: Determine the Shareholding Arrangement
Establish the ownership percentages, share classes and capital contribution arrangements.
Where multiple investors are involved, shareholders' agreements and governance provisions may be necessary.
Step 3: Complete Company Incorporation
The process of singapore company incorporation involves registration through ACRA's prescribed framework.
A foreign founder generally needs to engage a registered corporate service provider.
The company must satisfy requirements concerning directors, registered office arrangements and statutory officers.
Step 4: Appoint Directors and Company Secretary
A Singapore company must have at least one qualifying ordinarily resident director.
A company secretary must be appointed within six months of incorporation.
Directors are responsible for the company's management and statutory compliance.
Step 5: Establish Corporate Banking Arrangements
The holding company may require banking facilities to receive dividends, fund investments and manage international transactions.
Banks will independently assess ownership, beneficial owners, source of funds and expected activity.
Step 6: Implement Ownership and Governance Arrangements
Once incorporated, the group can proceed with relevant share acquisitions, subscriptions or restructuring transactions.
These steps may require approvals, filings and tax assessments in the jurisdictions concerned.
Step 7: Establish Accounting and Compliance Procedures
The company should maintain appropriate records of investments, dividend receipts, financing arrangements and related-party transactions.
A proper compliance framework helps support financial reporting and regulatory obligations.
Transfer Pricing and Intercompany Transactions
International holding structures frequently involve transactions between related entities.
These may include management fees, intercompany loans, guarantees, shared services and intellectual property arrangements.
Singapore generally applies the arm's length principle to related-party transactions.
This means that pricing should reflect terms that independent parties would agree to under comparable circumstances.
Where applicable, companies must maintain contemporaneous transfer pricing documentation.
For example, if a Singapore holding company provides genuine management services to its subsidiaries, the charges should be supported by the services performed and an appropriate pricing methodology.
Similarly, intercompany financing arrangements may require consideration of interest rates, credit risks and commercial terms.
Transfer pricing should not be treated merely as an accounting exercise. It should reflect the actual functions, assets and risks of the entities involved.
Ongoing Compliance for Singapore Holding Companies
A Singapore holding company remains subject to corporate compliance obligations even if it does not directly conduct trading activities.
Following company registration in singapore, ongoing requirements may include:
1. Maintaining statutory registers and corporate records.
2. Filing annual returns with ACRA.
3. Preparing financial statements.
4. Maintaining accounting records.
5. Meeting corporate income tax filing requirements.
6. Complying with applicable beneficial ownership disclosure rules.
7. Maintaining appropriate board and shareholder documentation.
8. Meeting audit requirements unless a relevant exemption applies.
9. Reviewing transfer pricing and related-party reporting obligations.
Where the company qualifies as a member of a multinational group, additional reporting or tax considerations may arise.
Larger groups should also evaluate whether international minimum tax rules, including applicable Pillar Two measures, affect their structure.
Compliance requirements should be reviewed periodically as the group expands or changes its ownership arrangements.
When Does a Singapore Holding Company Make Commercial Sense?
A Singapore holding structure may be suitable for businesses that have a clear commercial reason to centralise international ownership.
Examples include multinational groups expanding into Southeast Asia, investors acquiring businesses across several countries, and companies planning regional management functions.
It may also be relevant for groups seeking a structured platform for future investment rounds, acquisitions or strategic partnerships.
However, establishing a holding company creates additional costs and responsibilities.
These can include incorporation expenses, accounting and audit costs, corporate secretarial services, governance arrangements and international tax advisory requirements.
For businesses with limited overseas activity, the additional structure may not provide sufficient commercial value.
Before proceeding, groups should compare the expected benefits against ongoing costs, compliance obligations and tax implications in every relevant jurisdiction.
Common Mistakes to Avoid
International businesses should avoid establishing a Singapore holding company solely because the jurisdiction has an attractive reputation.
Common mistakes include:
1. Assuming all foreign dividends are automatically tax-exempt.
2. Believing Singapore incorporation guarantees tax residency.
3. Ignoring withholding taxes in subsidiary jurisdictions.
4. Establishing a company without genuine commercial objectives.
5. Overlooking transfer pricing requirements.
6. Assuming capital gains are always exempt from tax.
7. Failing to maintain appropriate governance documentation.
8. Ignoring the tax implications of restructuring existing subsidiaries.
A holding structure should be designed around the group's actual business needs and supported by appropriate legal, financial and tax analysis.
How YKG Global Helps You
YKG Global supports international businesses evaluating Singapore holding structures, cross-border expansion and corporate compliance requirements.
Our approach begins with understanding the group's ownership arrangements, investment objectives, operating jurisdictions and proposed business activities.
Depending on the agreed scope of engagement, our assistance may include:
1. Advisory support for Singapore holding company structures.
2. Evaluation of proposed ownership and subsidiary arrangements.
3. Coordination of incorporation documentation and registration requirements.
4. Guidance on director, company secretary and registered office arrangements.
5. Assistance with corporate documentation and governance requirements.
6. Coordination of accounting, tax and regulatory compliance services.
7. Support with international structuring and related-party transaction considerations.
8. Assistance with identifying cross-border tax and regulatory matters requiring specialist review.
For global groups, a holding company should support commercial growth while maintaining a sustainable and compliant corporate structure.
YKG Global helps clients assess the relevant requirements and coordinate appropriate professional support for their international expansion plans.