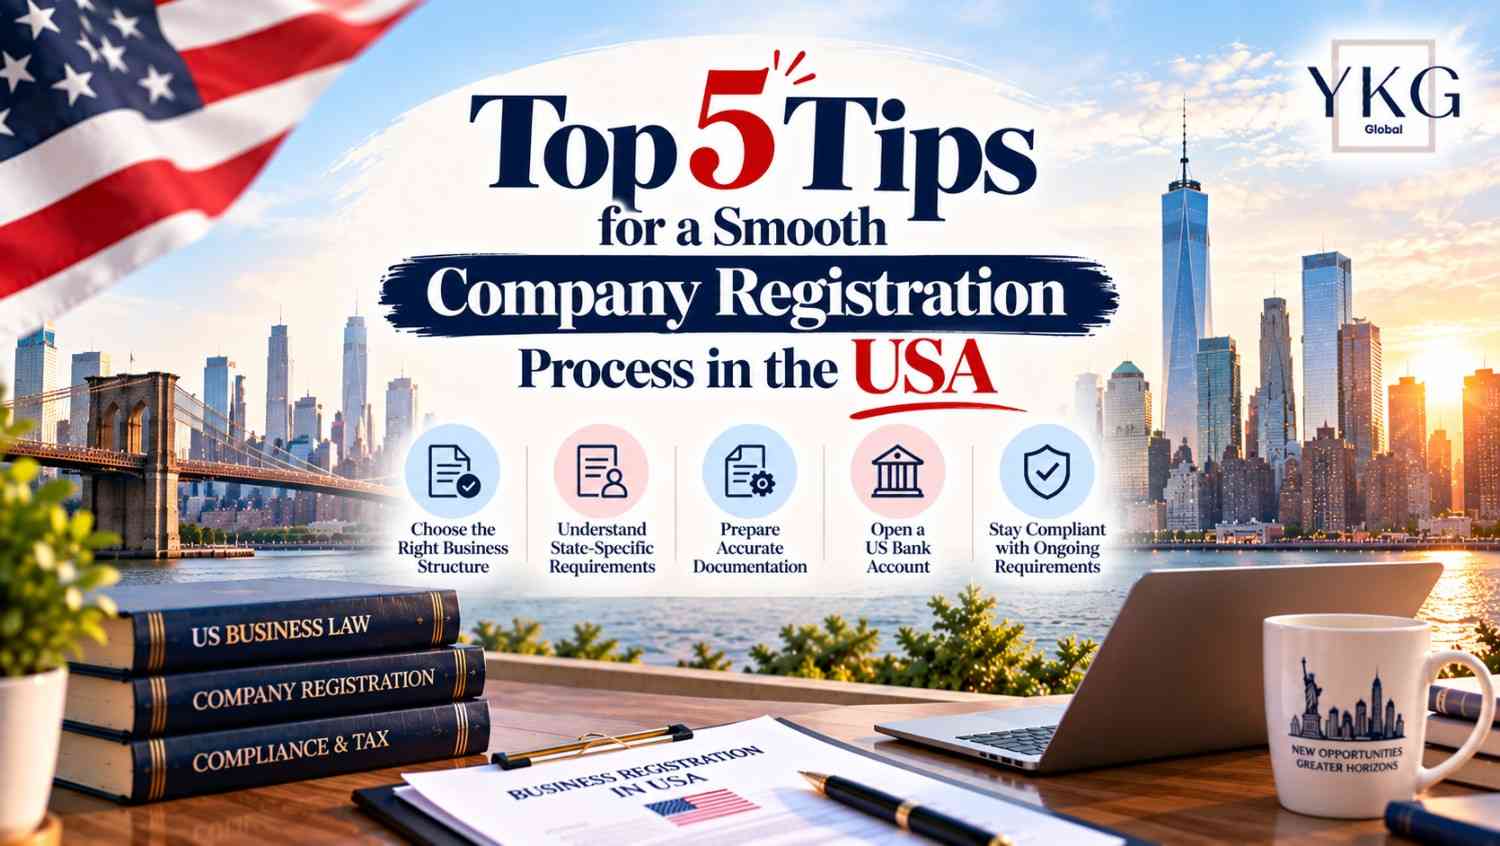
Top 5 Tips for Smooth Company Registration in USA
The United States offers businesses access to one of the world's largest consumer markets, a mature financial ecosystem, established legal institutions, and opportunities across industries such as technology, manufacturing, consulting, e-commerce, and international trade.
For foreign entrepreneurs and established companies, entering this market can create opportunities for growth, partnerships, and international expansion. However, setting up a business involves more than filing incorporation documents. Decisions about the state, legal structure, taxation, registered agent, and ongoing compliance can influence how efficiently the business operates.
A well-planned company registration in usa process helps entrepreneurs avoid preventable delays, unnecessary expenses, and administrative complications.
Here are five practical tips to help make the process smoother and establish a strong foundation for your US business.
1. Choose the Right State Before Registering
One of the first decisions is determining where to form your business. The USA does not have a single nationwide company incorporation process for all business entities. LLCs and corporations are generally formed under state law, and requirements differ between states.
Entrepreneurs often compare Delaware, Wyoming, Florida, Texas, and other states. However, the most popular state is not automatically the best choice for every business.
What should you evaluate?
1. Business operations: Where will your office, employees, warehouse, or other physical operations be located?
2. State filing requirements: What documents, reports, and recurring filings will the state require?
3. Tax implications: Consider state taxes, franchise taxes, and other applicable obligations.
4. Foreign qualification: If you form an entity in one state but conduct business in another, you may need to register in the second state as well.
5. Commercial priorities: Consider your customers, investors, suppliers, and operational requirements.
For example, a business operating primarily in Texas should evaluate the requirements and costs of forming and operating there before choosing Delaware solely because it is popular among corporations.
Registering in multiple states can create additional reporting and fee obligations. Choose a state based on your actual business plans rather than assumptions about tax savings or incorporation speed.
2. Select the Appropriate Business Structure
The right legal structure affects ownership, liability, taxation, management, and reporting responsibilities. Before proceeding with company registration in america, determine which structure best fits your business model.
1. Limited Liability Company (LLC)
An LLC is a popular option for many small businesses, consultants, service providers, and international entrepreneurs. It generally provides liability protection to its owners, known as members, subject to applicable legal exceptions.
For federal tax purposes, an LLC's classification depends on factors such as the number of members and any tax elections made. A single-member LLC is generally treated as a disregarded entity by default, while a multi-member LLC is generally treated as a partnership unless it elects another permitted classification.
2. Corporation
A corporation is a separate legal entity that may be suitable for businesses seeking outside investment, issuing shares, or establishing a more formal governance structure.
A C corporation is generally subject to corporate-level federal income tax, and shareholders may also be taxed on dividends. Eligible corporations may consider an S corporation election, but strict eligibility requirements apply. Nonresident aliens generally cannot be shareholders of an S corporation.
3. Sole Proprietorship
A sole proprietorship may be appropriate for certain small businesses operated by an individual. However, it does not provide the same separation between the owner and the business as an LLC or corporation.
3. How should you decide?
Consider the number of owners, investment plans, liability exposure, expected income, tax residency, and whether the business will operate internationally.
An LLC may be a practical starting point for some founders, but it is not universally the best option. Cross-border tax advice is especially important for foreign-owned entities because US reporting obligations may apply even when the business has limited US operations.
4. Prepare the Required Documents and Verify the Company Name
Incomplete documentation and avoidable filing errors can delay the incorporation process. Preparing the necessary information before submitting an application helps reduce back-and-forth with the relevant state authority.
1. Check name availability
Your proposed business name must comply with the chosen state's naming rules. Search the relevant state's business entity database to check for conflicting names and confirm whether the name is available.
State-level name approval does not automatically grant nationwide trademark protection. If the brand is important to your business, consider conducting a separate trademark search.
2. Gather the incorporation information
Depending on the state and structure, you may need:
- The proposed company name and principal business address.
- Details of the owners or members.
- Information about the managers or directors, where applicable.
- The registered agent's name and physical address in the state.
- Articles of Organization for an LLC or Articles of Incorporation for a corporation.
- Additional declarations or information required by the relevant state.
Foreign founders may also need to prepare passport details, overseas company documents, and other identification or ownership information requested by service providers, banks, or authorities.
Understand the registered agent requirement
An LLC or corporation generally needs a registered agent in its formation state. The agent receives official notices, legal correspondence, and service of process for the entity.
A registered agent is not necessarily the company's owner, director, manager, or authorised representative for banking. Understand the scope of the service before appointing one.
5. Plan for EIN, Tax Registration, and Banking
Receiving state approval is an important milestone, but it does not complete every requirement needed to operate a business.
A smooth llc registration in usa process should include planning for federal tax identification, state-level tax obligations, licensing, and banking.
6. Apply for an Employer Identification Number (EIN)
An EIN is a federal tax identification number issued by the Internal Revenue Service (IRS). Businesses commonly need one for federal tax administration, hiring employees, and opening business bank accounts.
The appropriate sequence is generally to establish the legal entity first and then apply for the EIN.
International founders should note that the online EIN application is not available to every applicant. Businesses whose principal place of business is outside the United States may need to use an alternative IRS application method, such as the applicable telephone, fax, or mail process.
An EIN application is free when submitted directly to the IRS.
7. Identify state and local tax obligations
Depending on the business and its activities, additional registrations may be required for sales tax, employer taxes, franchise taxes, or other state and local obligations.
For example, a business selling taxable products may need sales tax registration in a state where it has the relevant obligations. Requirements vary by jurisdiction and business activity.
8. Prepare for banking requirements
A US company may seek a business bank account after incorporation and tax identification. However, incorporation and an EIN do not guarantee bank account approval.
Financial institutions conduct their own due diligence and may request identity documents, ownership information, business activity details, evidence of the company's address, and information about the source of funds.
Foreign founders should confirm the bank's documentation and onboarding requirements before assuming that the process can be completed remotely.
9. Understand Ongoing Compliance Before You Incorporate
The final tip is to plan beyond the registration date. A company must maintain the filings, records, and tax arrangements that apply to its legal structure and jurisdictions.
When founders register llc in usa, they should create a compliance calendar covering applicable state, federal, and local obligations.
Key responsibilities to consider
1. Annual reports and state filings: Some states require periodic reports, renewal filings, or franchise tax payments.
2. Federal and state tax returns: Filing obligations depend on the entity's tax classification, ownership, income, and activities.
3. Accounting records: Maintain accurate financial records and supporting documents.
4. Business licences: Certain industries and locations require permits or licences before operations begin.
5. Employment obligations: Hiring staff may trigger payroll, withholding, unemployment insurance, and other requirements.
6. Changes to company information: Changes in registered agents, addresses, management, or other reportable details may need to be filed with the relevant state.
Foreign-owned US entities may have additional federal information-reporting obligations. For example, a foreign-owned single-member LLC treated as a disregarded entity may be required to file Form 5472 with a pro forma Form 1120 when the applicable conditions are met.
Beneficial ownership reporting rules have also changed in recent years. Check the current requirements applicable to your entity rather than relying on outdated online guidance.
Planning these obligations early can help protect the company's good standing and reduce the risk of missed filings or penalties.
10. Common Mistakes to Avoid During US Company Registration
Even a straightforward incorporation can become complicated when key decisions are made without considering the full business context.
Avoid these common mistakes:
1. Selecting a state based only on popularity rather than operational needs.
2. Choosing an LLC or corporation without reviewing its tax implications.
3. Assuming an EIN replaces state and local registrations.
4. Using an address or registered agent arrangement that does not meet state requirements.
5. Assuming incorporation automatically guarantees a bank account.
6. Ignoring reporting obligations that apply to foreign-owned entities.
7. Treating registration as a one-time task rather than an ongoing compliance responsibility.
A clear incorporation plan should address the entity, its ownership, tax treatment, operating location, and post-registration obligations together.
11. How YKG Global Helps You
YKG Global supports entrepreneurs and international businesses planning to establish a US presence. Our team can assist with evaluating the proposed entity structure, coordinating incorporation documentation, and identifying relevant tax, registration, and compliance considerations.
For international founders, usa company registration should be approached as part of a broader market-entry plan. Understanding ownership arrangements, state requirements, federal tax identification, banking documentation, and continuing reporting responsibilities can help create a more organised setup process.
The appropriate approach depends on the company's activities, ownership, and intended operating locations. Where required, founders should obtain advice from qualified US legal and